 Product
 Brand
 Articles
 Tools

Organic Semiconductor Market Set to Reach USD 843.62 Billion by 2032, Driven by Rising Demand for Flexible Electronics
Emergen Research has predicted that the global Organic Semiconductor market will reach USD 843.62 billion by 2032, growing at a compound annual growth rate of 21.8%. This growth is primarily driven by the rising demand for flexible electronics. The by-products of the fossil fuel industry, often burnt if no other use is found for them, are most frequently used to produce organic semiconductors. These by-products are chemically altered to create value-added products for various applications, including solar cells. However, the market's growth could be hampered by limited performance and stability. Organic semiconductors often perform better and are more unstable compared to inorganic semiconductors. Additionally, the complexity of manufacturing and competition from inorganic semiconductors could also restrain market growth. Organic semiconductors require more complex fabrication techniques than inorganic ones. Therefore, scalable and economical production procedures must be developed for organic semiconductor-based products to be widely used. The market is dominated by a few large and medium-sized players, including BASF SE, DuPont De Nemours, Inc., Koninklijke Philips N.V., LG Electronics, Merck KGaA, Novaled GmbH, Samsung, Sony Corporation, Sumitomo Corporation, and Universal Display. These companies are deploying various strategies, entering into mergers & acquisitions, strategic agreements & contracts, and developing, testing, and introducing more effective organic semiconductors. The North American market accounted for the largest revenue share in 2022, driven by increasing investments and Research and Development (R&D) activities in the region. For instance, the University of North Carolina in Chapel Hill is leading a team of four universities that have been given USD 7.5 million by the U.S. Department of Defense to develop organic semiconductors for the next generation of electronics.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20255074
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 20261100
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 20261208
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261694
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More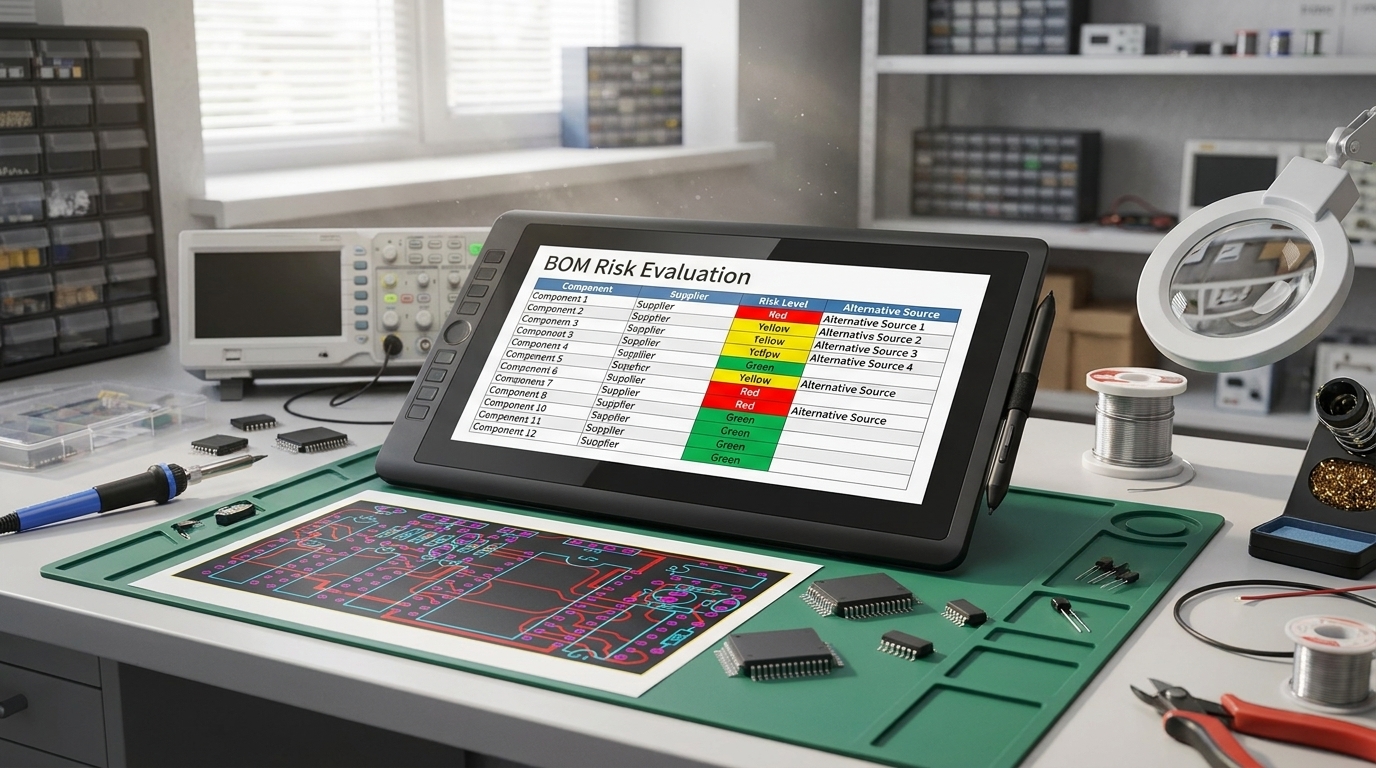 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026476
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![D38999/24CE11SC]() D38999/24CE11SC
Corsair Electrical Connectors
![GTS06R16-11SZ-023]() GTS06R16-11SZ-023
Amphenol
![GTCG06AF24-9SY]() GTCG06AF24-9SY
Amphenol
![EKMC1606112]() EKMC1606112
Panasonic Electric Works
![EKMC1606111]() EKMC1606111
Panasonic Electric Works
![FLUKE-177 ESFP]() FLUKE-177 ESFP
Fluke Electronics
![PA3209NL]() PA3209NL
Pulse Electronics Power
![06-0100-30/37191(AAD)]()
![04980932.X]() 04980932.X
Littelfuse Inc.
![0201B103K250CT]() 0201B103K250CT
Walsin Technology Corporation