 Product
 Brand
 Articles
 Tools

European Chipmakers Experience Decline Following SMIC's Profit Slump
European chipmakers faced a dip in their stock prices on Friday, mirroring the fall in some Asian semiconductor companies. This decline comes after China's Semiconductor Manufacturing International Corp (SMIC) reported an 80% decrease in its quarterly income. SMIC's profit attributable to owners dropped to approximately $94 million in the three months ending September 30, a significant decline from the $470.8 million recorded in the same period last year. Additionally, the company's quarterly revenue decreased by 15% to $1.62 billion, and its gross margin nearly halved to 19.8% from 38.9% in the previous year. The chipmaker also predicted an even lower gross margin in the fourth quarter and highlighted higher capital expenditures for 2023. These projections were made due to a drop in capacity utilization caused by sluggish demand for semiconductors. Following SMIC's announcement, its Hong Kong shares experienced a 6.8% decline, while shares of rival company Hua Hong Semiconductor Ltd plummeted over 15%. The impact of these losses spread to Europe, where semiconductor equipment maker ASML, the largest tech firm on the continent, saw a slight decrease in mid-morning trading. Other European chipmakers, such as Infineon Technologies and STMicroelectronics, also experienced slumps of over 2%, while ASM International in the Netherlands lost 1.6%. SMIC's disappointing results come after TSMC, Samsung, and SK Hynix reported dismal quarterly performances, indicating a sustained weakness in global chip demand. Additionally, ASML reported lower-than-expected orders in its latest quarter and issued a rare warning regarding an uncertain recovery in customer spending. Major chipmakers have been grappling with declining demand following a significant rise in interest rates over the past year. Furthermore, doubts have been raised about the long-term impact of the development of generative artificial intelligence (AI) on chip demand. Softbank's Arm, which designs chips used by major semiconductor manufacturers, also reported weak quarterly results and projected disappointing revenue and profit figures for the current quarter. Apple, a major customer for Asian chip firms, has also experienced four consecutive quarters of declining sales. It remains to be seen how the chip market will navigate these challenges and whether demand will rebound in the near future.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20255053
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 20261079
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 20261169
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261653
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More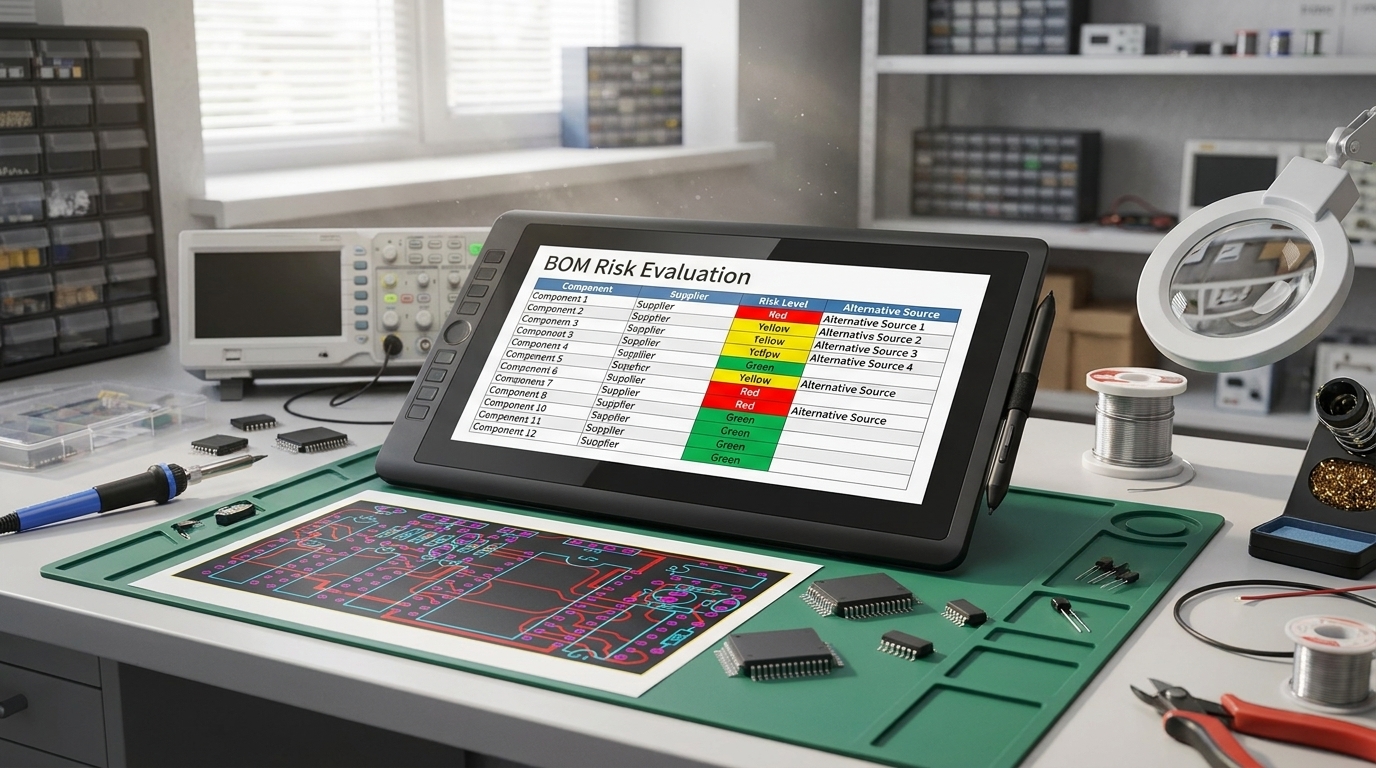 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026456
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![BLM18PG121SN1D]() BLM18PG121SN1D
Murata Electronics
![TP3420AV309]() TP3420AV309
Texas Instruments
![19-217/R6C-AL1M2VY/3T]() 19-217/R6C-AL1M2VY/3T
Everlight Electronics Co Ltd
![MPZ2012S102AT000]() MPZ2012S102AT000
TDK Corporation
![SE2537L-R]() SE2537L-R
Skyworks Solutions Inc.
![SKY81294-14-001]() SKY81294-14-001
Skyworks Solutions Inc.
![HMC588LC4BTR]() HMC588LC4BTR
Analog Devices Inc.
![80HCPS1432CRM]() 80HCPS1432CRM
Renesas Electronics America Inc.
![DS21Q48N]() DS21Q48N
Maxim Integrated
![ALT6702RM45Q7]() ALT6702RM45Q7
Skyworks Solutions Inc.