 Product
 Brand
 Articles
 Tools

Global Semiconductor Market Share Continues to Grow
According to the latest data from the Semiconductor Industry Association (SIA), the global semiconductor market share is on a steady rise. The report reveals that Taiwan, Europe, Japan, China, South Korea, and the United States are the key players in this industry. In 2022, Taiwan held the highest market share at 48 percent, followed by Europe and Japan. China, South Korea, and the United States also contributed significantly to the global semiconductor market. The increasing demand for semiconductors can be attributed to various factors. One of the key drivers is the growing adoption of advanced technologies such as artificial intelligence (AI), Internet of Things (IoT), and 5G. These technologies require powerful and efficient semiconductors to support their operations.
Additionally, the COVID-19 pandemic has accelerated the digital transformation across industries, leading to an increased need for semiconductors. From remote work and online learning to telemedicine and e-commerce, the reliance on technology has surged, driving the demand for semiconductors. Furthermore, the automotive industry is also a significant contributor to the semiconductor market. The rise of electric vehicles (EVs) and autonomous driving systems has created a surge in demand for semiconductors used in these vehicles. The SIA report highlights the importance of collaboration between countries to ensure a stable supply chain for semiconductors. The industry heavily relies on international trade and cooperation to meet the growing demand. However, the global semiconductor market is not without challenges. The ongoing chip shortage has impacted various industries, including automotive, consumer electronics, and telecommunications. The shortage has resulted in production delays and increased prices. To address this issue, governments and companies are investing in expanding semiconductor manufacturing capacity. Efforts are being made to diversify the supply chain and reduce dependence on a few key players. In conclusion, the global semiconductor market is witnessing steady growth, driven by the increasing demand for advanced technologies and the digital transformation across industries. Taiwan, Europe, Japan, China, South Korea, and the United States are the major players in this market. Collaboration and investment in expanding manufacturing capacity are crucial to ensure a stable supply chain and overcome challenges such as the ongoing chip shortage.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20255053
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 20261079
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 20261169
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261653
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More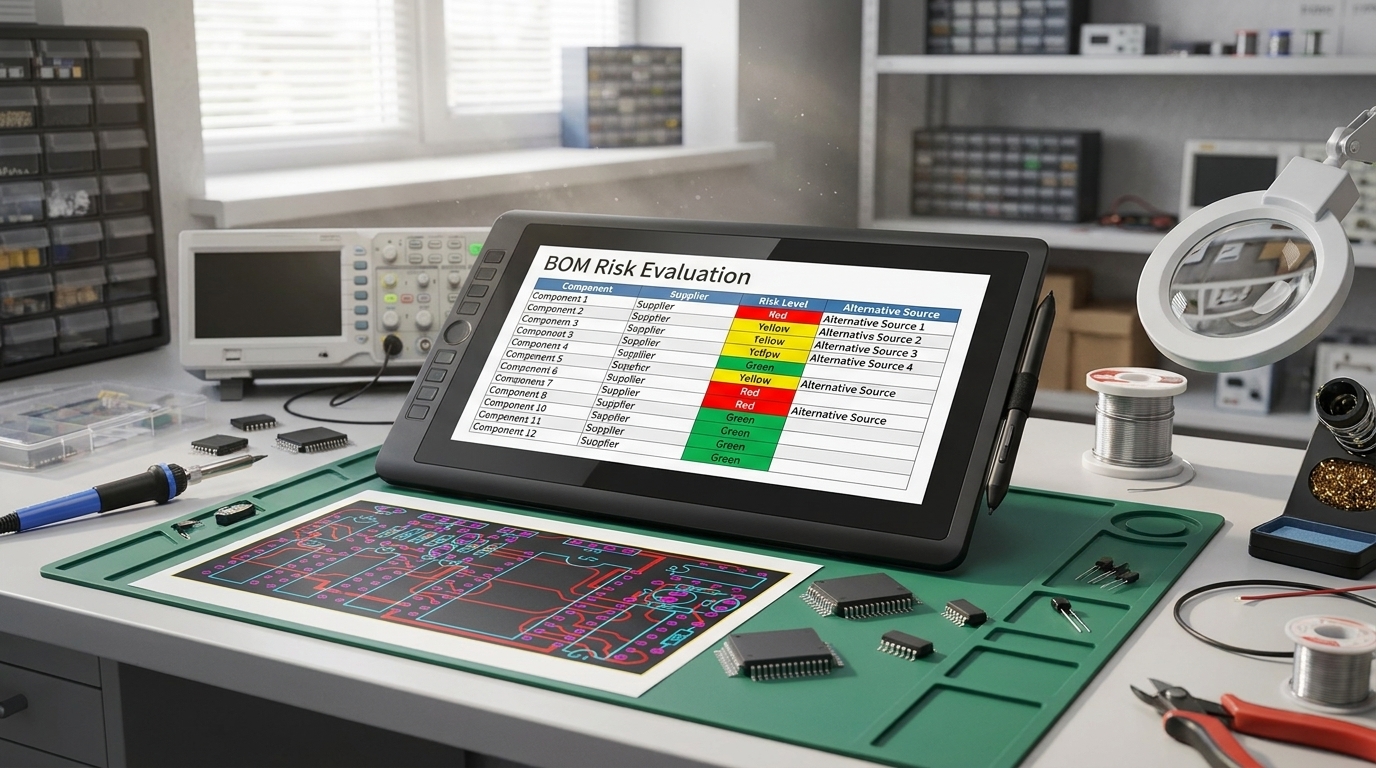 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026456
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![BLM18PG121SN1D]() BLM18PG121SN1D
Murata Electronics
![TP3420AV309]() TP3420AV309
Texas Instruments
![19-217/R6C-AL1M2VY/3T]() 19-217/R6C-AL1M2VY/3T
Everlight Electronics Co Ltd
![MPZ2012S102AT000]() MPZ2012S102AT000
TDK Corporation
![SE2537L-R]() SE2537L-R
Skyworks Solutions Inc.
![SKY81294-14-001]() SKY81294-14-001
Skyworks Solutions Inc.
![HMC588LC4BTR]() HMC588LC4BTR
Analog Devices Inc.
![80HCPS1432CRM]() 80HCPS1432CRM
Renesas Electronics America Inc.
![DS21Q48N]() DS21Q48N
Maxim Integrated
![ALT6702RM45Q7]() ALT6702RM45Q7
Skyworks Solutions Inc.