 Product
 Brand
 Articles
 Tools

Semiconductor R&D Spending: Top 12 Countries
The semiconductor industry is at the heart of the digital economy, with applications in numerous sectors including communication, healthcare, automotive, and military systems. A recent report from Fortune Business Insights valued the global semiconductor market at $573.44 billion in 2022, and projected growth to reach $1.3 trillion by 2029. This report also highlighted the key role of research and development (R&D) in driving this growth. China currently holds the largest share of the semiconductor market, but North America is predicted to experience the most growth during the forecast period. The communication and networking segment currently holds the largest share of the semiconductor market, and is anticipated to significantly contribute to the growth of the semiconductor industry in Europe during the forecast period. The top 12 countries in terms of semiconductor R&D spending are China, Japan, South Korea, Taiwan, Hungary, the United Kingdom, Italy, France, Germany, the United States, the Netherlands, and Israel. These countries are investing heavily in R&D to keep up with the booming demand for semiconductors and to tackle the global semiconductor shortage crisis. In recent years, there has been a surge in demand for semiconductors, which has led to a global semiconductor shortage crisis. To address this issue, many countries and governments have been taking steps to support the semiconductor industry. For example, in August 2022, the American government enacted the CHIPS and Science Act to facilitate the semiconductor industry and reinforce the country's national security. The rising geopolitical tensions, particularly between the US and China, have also made countries and governments more conscious of the future of their semiconductor industries. The US government has started regulating the sales of semiconductor chips to China, which has led to a tug-of-war between the two superpowers over semiconductors. In response to these challenges, governments across the world have become active participants in the semiconductor race. For instance, the Chinese government has income tax exemptions for advanced technology process nodes to stimulate the integrated circuits industry's development locally. The European Commission passed the EU Chips Act in April 2023, with the intention of doubling Europe's share in global chip production by 2030. The Japanese government is also investing heavily in chip manufacturing, as evidenced by its funding to Rapidus, a state-organized joint chip venture.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20254828
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 2026898
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 2026818
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261300
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More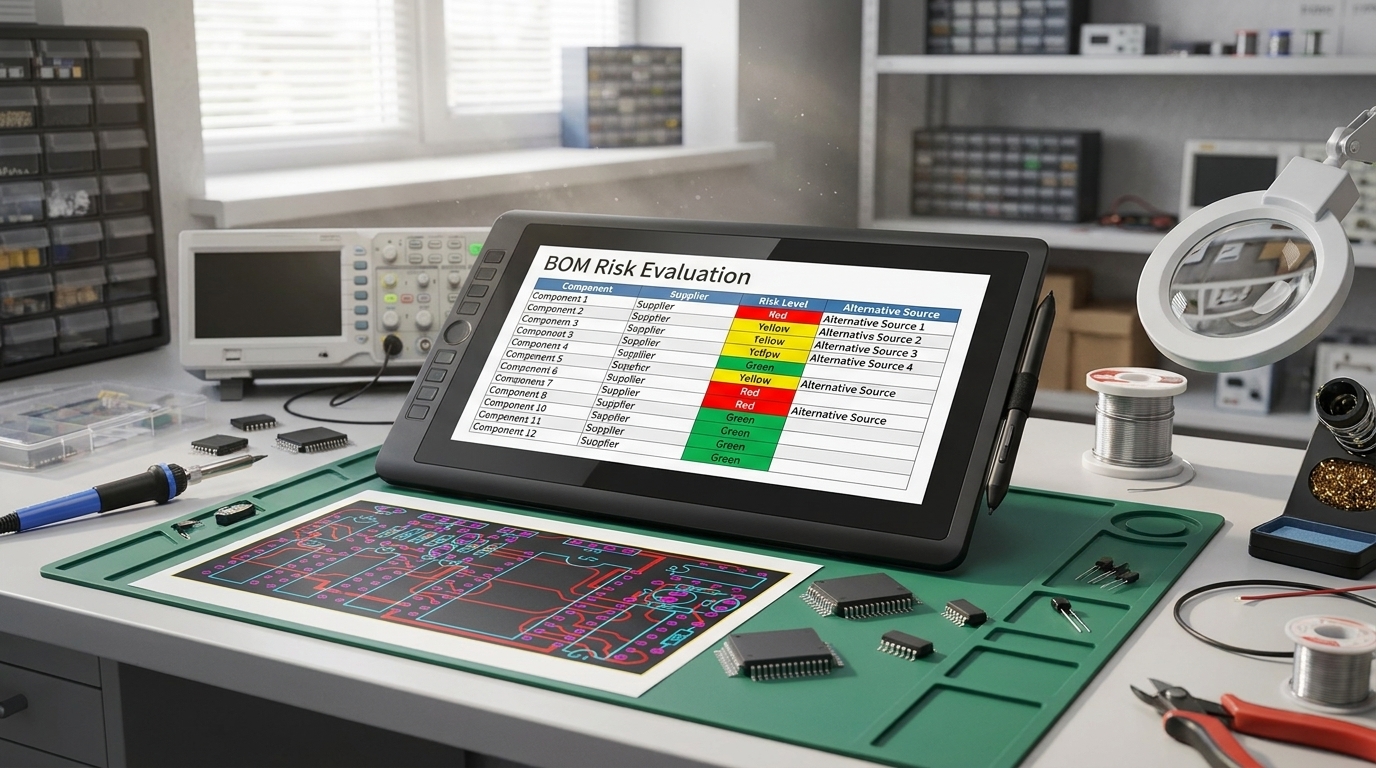 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026296
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![10207101009]() 10207101009
Littelfuse Inc.
![BLM03AX601SZ1D]() BLM03AX601SZ1D
Murata Electronics
![74AHC74D,118]() 74AHC74D,118
Nexperia USA Inc.
![02540101Z]() 02540101Z
Littelfuse Inc.
![CJ25-82010]() CJ25-82010
Nidec Copal Electronics
![162GB-16F18-11PB]() 162GB-16F18-11PB
Amphenol
![H200X064H1T-2-B]() H200X064H1T-2-B
Panduit Corp
![SLB-25MG3F]() SLB-25MG3F
ROHM Semiconductor
![PEC11R-4220F-S0024]() PEC11R-4220F-S0024
Bourns Inc.
![BLM03AX121SZ1D]() BLM03AX121SZ1D
Murata Electronics