 Product
 Brand
 Articles
 Tools

Robotics and Semiconductor Industries Face Challenges and Opportunities
The North American robotics market saw a significant decline in the second quarter of 2023, with robot orders falling by 37% between April and July, a 20% drop in value, compared to the same period in 2022, according to the Association for Advancing Automation (A3).
The slowdown is attributed to a sluggish economy and high interest rates, despite the ongoing labor challenges that robots have been able to address effectively since the COVID-19 pandemic. Interestingly, the semiconductor and electronics industries have shown the strongest overall demand for robots during this period. However, the non-automotive sector purchased 52% of the robots sold in Q2 2023, with total sales in that sector down by 20%. The remaining 48% of robots purchased went to the automotive industry, with total orders down by 49%.
In related news, the U.S. Department of Defense announced fresh funding for a program aimed at developing the microelectronics workforce required by the armed forces. The program, known as Scalable Asymmetric Lifecycle Engagement (SCALE), is led by Purdue University and includes 18 other institutions. The program, which received an additional $19 million in funding, focuses on radiation-hardened microelectronics and trusted artificial intelligence tools, in addition to training and continuing education.
Flexpipe, a modular system equipment company, has also introduced Lean Maker Academy, a free online certification program designed to teach employees how to assemble modular system equipment at their own pace. The program consists of interactive video lessons and quizzes, with the first course covering tubular systems.
Lastly, a study from the Freedonia Group predicts that demand for robots to perform tasks such as mowing lawns, shoveling driveways, and cleaning pools will grow by 24% per year through 2027. The rise in demand is attributed to people returning to the office and lacking time for yard work, labor shortages affecting the supply of human landscapers, and a slew of innovations waiting to be improved upon.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20255074
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 20261100
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 20261208
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261694
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More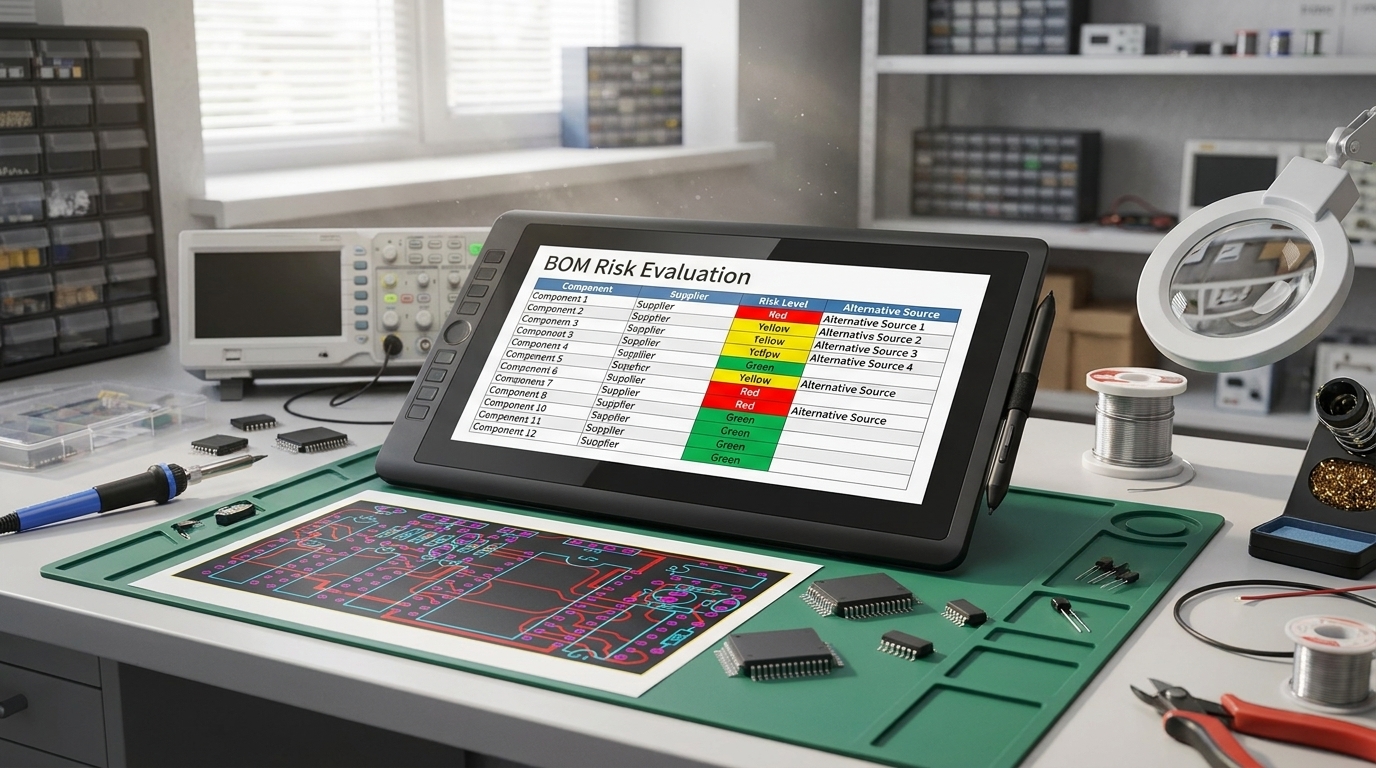 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026476
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![D38999/24CE11SC]() D38999/24CE11SC
Corsair Electrical Connectors
![GTS06R16-11SZ-023]() GTS06R16-11SZ-023
Amphenol
![GTCG06AF24-9SY]() GTCG06AF24-9SY
Amphenol
![EKMC1606112]() EKMC1606112
Panasonic Electric Works
![EKMC1606111]() EKMC1606111
Panasonic Electric Works
![FLUKE-177 ESFP]() FLUKE-177 ESFP
Fluke Electronics
![PA3209NL]() PA3209NL
Pulse Electronics Power
![06-0100-30/37191(AAD)]()
![04980932.X]() 04980932.X
Littelfuse Inc.
![0201B103K250CT]() 0201B103K250CT
Walsin Technology Corporation