 Product
 Brand
 Articles
 Tools

Vietnam's Semiconductors Market to Grow Rapidly due to Smartphone Adoption
The Semiconductors Market in Vietnam is projected to see a significant growth with a Compound Annual Growth Rate (CAGR) of 6.12% between 2022 and 2027, leading to a substantial increase in market size, amounting to USD 1.66 billion. This growth is driven by the increasing number of smartphone users, investments in the developing semiconductor industry, and the growing use of Internet of Things (IoT). Vietnam's rapid adoption of smartphones, with 61.3 million users, is a key driver of the semiconductors market growth. This is due to the rising living standards, availability of premium devices at affordable prices, and government's emphasis on 5G development. Companies are establishing more factories in Vietnam to meet the demand, exporting 40 mobile phone brands, including Sony and Samsung. The increasing number of smart homes in Vietnam, driven by technology offering comfort, convenience, security, and energy efficiency, is also expected to boost the semiconductor market growth. These homes rely on intelligent appliances, mobile devices, and home automation systems with integrated circuits, all dependent on semiconductors. However, one of the challenges affecting the market growth is the scarcity of skilled labour in Vietnam. The semiconductor industry, despite its potential for expansion, faces a shortage of workers with the necessary skills, leading to high wages or investment in training. Companies in the Semiconductors Market in Vietnam are deploying strategies like strategic alliances, partnerships, mergers and acquisitions, geographical expansion, and product/service launches to strengthen their market presence. Notable market players include Advanced Micro Devices Inc., Broadcom Inc., Fuji Electric Co. Ltd., Hitachi Ltd., Infineon Technologies AG, Intel Corp., Microchip Technology Inc., NVIDIA Corp., NXP Semiconductors NV, ON Semiconductor Corp., Qualcomm Inc., Renesas Electronics Corp., Samsung Electronics Co. Ltd., Semiconductor Manufacturing International Corp., and STMicroelectronics NV.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20255053
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 20261079
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 20261169
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261653
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More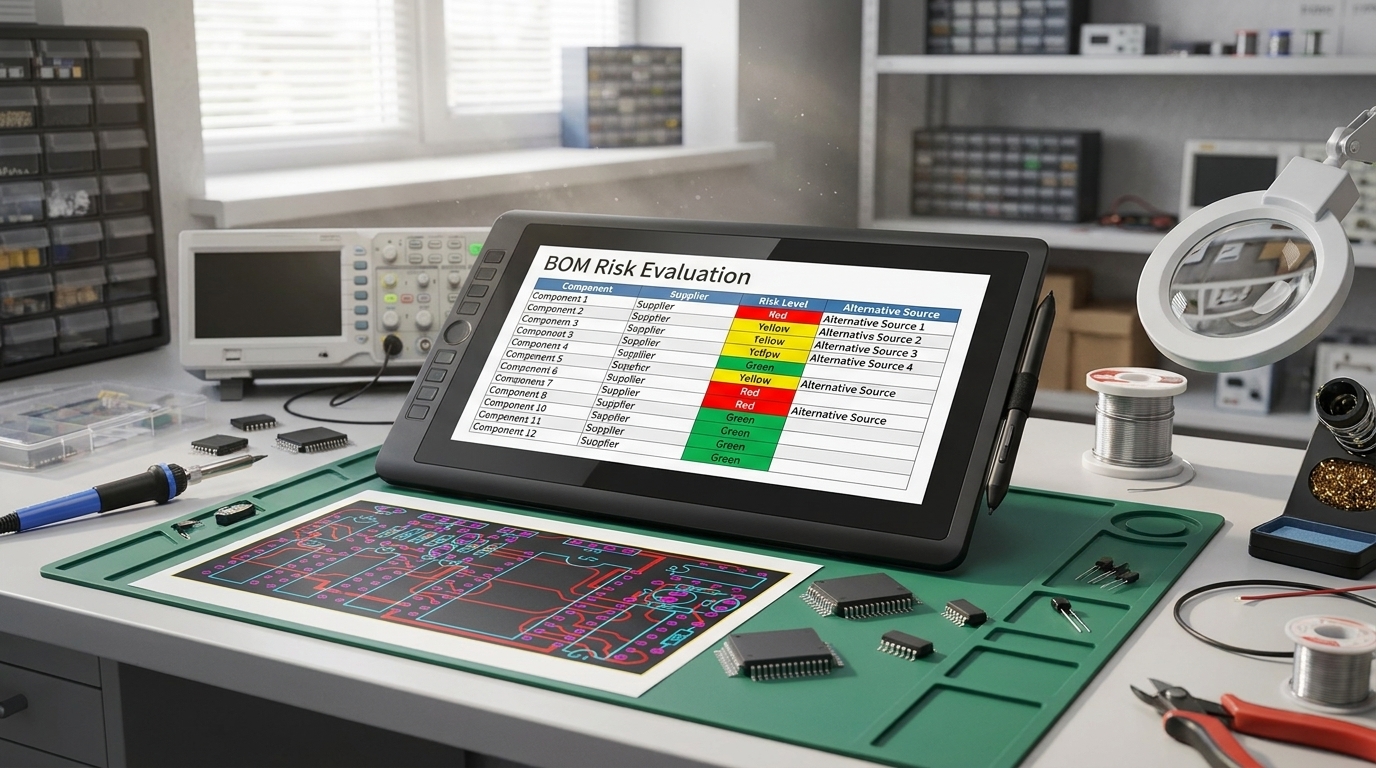 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026456
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![BLM18PG121SN1D]() BLM18PG121SN1D
Murata Electronics
![TP3420AV309]() TP3420AV309
Texas Instruments
![19-217/R6C-AL1M2VY/3T]() 19-217/R6C-AL1M2VY/3T
Everlight Electronics Co Ltd
![MPZ2012S102AT000]() MPZ2012S102AT000
TDK Corporation
![SE2537L-R]() SE2537L-R
Skyworks Solutions Inc.
![SKY81294-14-001]() SKY81294-14-001
Skyworks Solutions Inc.
![HMC588LC4BTR]() HMC588LC4BTR
Analog Devices Inc.
![80HCPS1432CRM]() 80HCPS1432CRM
Renesas Electronics America Inc.
![DS21Q48N]() DS21Q48N
Maxim Integrated
![ALT6702RM45Q7]() ALT6702RM45Q7
Skyworks Solutions Inc.