 Product
 Brand
 Articles
 Tools

Semiconductor Sales Expected to Rebound in 2024, Driven by Innovation
Global semiconductor sales are projected to bounce back in 2024, fueled by a frenzy of innovation. The surge in sales will be driven by fierce competition, significant investments by chip firms and governments, and rapid advancements in manufacturing. The growth will be primarily attributed to the increasing demand for artificial intelligence (AI) chips, particularly generative AI tools that can perform various tasks like composing text, writing computer code, and creating images. World Semiconductor Trade Statistics estimates that global semiconductor sales will rise by 13% in 2024, reaching $590 billion, following a 9% decline in 2023. The U.S. market is expected to experience strong sales growth in high-end chips, with memory sales projected to soar by 45% in 2024. This positive outlook bodes well for companies like Samsung, SK Hynix, and Micron. Integrated circuits are also expected to see a sales jump of 16%, benefiting vendors of high-end CPUs and GPUs such as Nvidia, Intel, AMD, MediaTek, and Qualcomm. While prospects for other chips used in automobiles, industry, and the Internet of Things are relatively weaker, they are still anticipated to achieve single-digit growth. The forecast highlights the increasing competition in the AI chip market, with Nvidia currently leading the pack but facing competition from AMD, Intel, and Huawei. Leading chip manufacturers like Taiwan Semiconductor Manufacturing Co., Intel, and Samsung are pushing the boundaries of chipmaking to stay ahead. The innovation at these manufacturers is expected to result in custom AI chips with significant performance improvements. Noteworthy developments in 2024 include more powerful data center chips from Nvidia, AI chips for smartphones and laptops with extended battery life, and smartphones capable of converting text to images and identifying the best facial expressions in photos. The rebound in semiconductor sales indicates a positive outlook for the industry and suggests a promising future for technological advancements.
 UTMEL

We are the professional distributor of electronic components, providing a large variety of products to save you a lot of time, effort, and cost with our efficient self-customized service. careful order preparation fast delivery service
 Power Semiconductor Procurement After the Nexperia Shake-Up—NXP for Stability, ON for Technology, or Nexperia for Value?UTMEL04 November 20254807
The recent supply chain turmoil surrounding Netherlands-based Nexperia has sent shockwaves through the global semiconductor industry, forcing procurement professionals to re-evaluate their sourcing strategies.
Read More AI Computing Power Gap: How Token Consumption is Reshaping Server Component SourcingUTMEL23 June 2026889
As global token consumption drives the transition to high-density 100kW+ AI data centers, power delivery networks require advanced Wide-Bandgap semiconductors (SiC/GaN) and high-capacitance MLCCs. This shift has triggered a component procurement crisis with lead times exceeding 24 weeks. To bypass shortages, hardware buyers must abandon just-in-time manufacturing and leverage independent global distributor networks to secure critical power and passive components.
Read More The BSPDN Revolution: Overcoming IR Drop in Sub-2nm GAAFET Nodes with Backside Power DeliveryUTMEL25 June 2026793
As semiconductor manufacturing enters the sub-2nm era, Backside Power Delivery Networks (BSPDN) are replacing traditional front-side routing to overcome critical IR drop bottlenecks. By separating power and signal delivery, chipmakers like Intel and TSMC drastically improve performance and density in GAAFET designs. However, this radical shift introduces manufacturing complexities, thermal challenges, and demands advanced packaging and power management solutions.
Read More Power Management ICs Trends 2026: AI Demand, Supply Risks, and Sourcing StrategiesUTMEL06 July 20261265
As AI server racks surpass 100kW by 2026, data centers are shifting toward wide-bandgap semiconductors like SiC and GaN. However, this demand has triggered a critical shortage of mature-node Power Management ICs (PMICs). To prevent production halts, sourcing teams must abandon 'just-in-time' models, implement proactive 'just-in-case' strategies, and rapidly qualify pin-to-pin alternative components to secure their supply chains.
Read More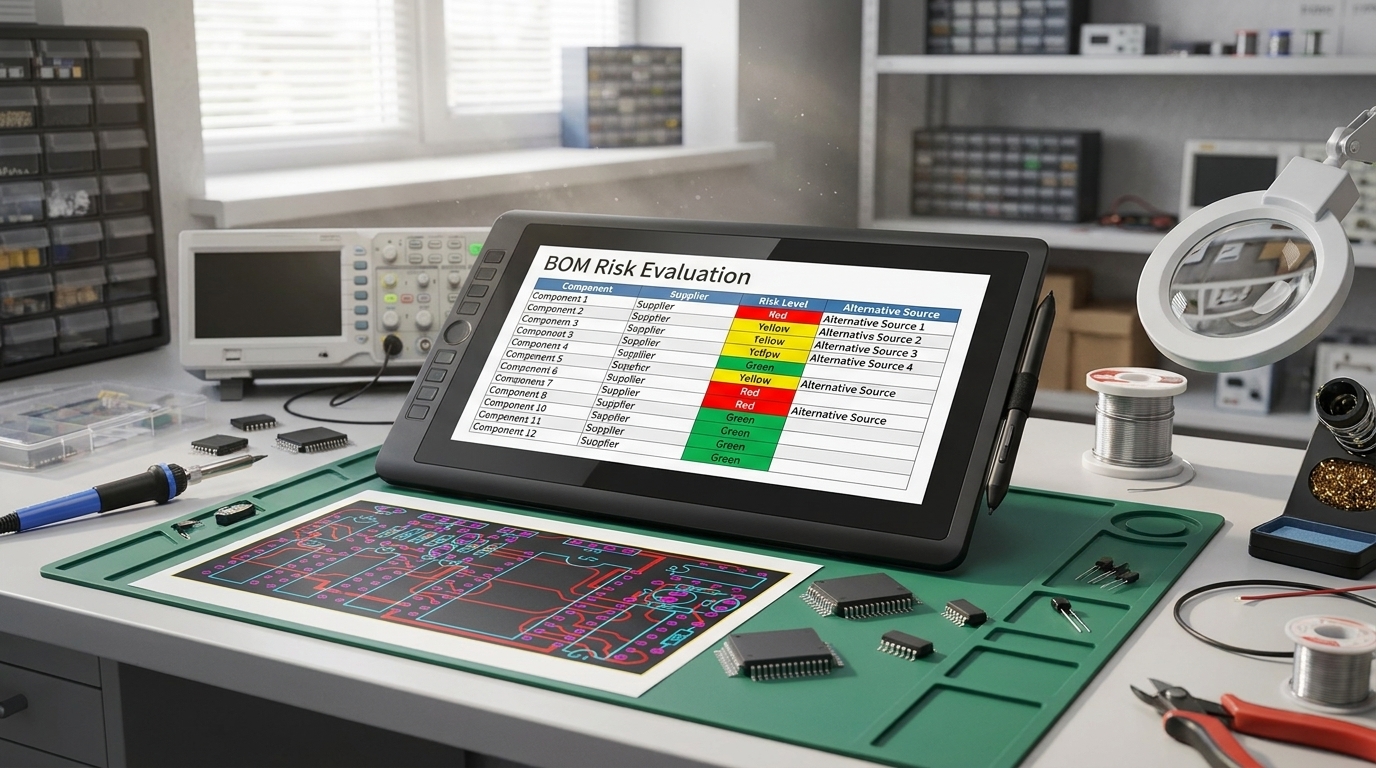 onsemi Synaptics Acquisition Impact: BOM Risk Checklist and Second-Source Strategy for Edge AI DesignsUTMEL27 July 2026287
The onsemi acquisition of Synaptics provides hardware program managers a 12-to-18-month window before potential product cancellations occur in mid-2027. This guide outlines how to audit BOM exposure across overlap and non-core product lines, calculate Last-Time-Buy volumes including hidden storage costs, establish proactive second-sourcing triggers, and implement supply chain monitoring to prevent line-down events.
Read More
Subscribe to Utmel !
![BLM15BD102SN1D]() BLM15BD102SN1D
Murata Electronics
![H050X034H1T]() H050X034H1T
Panduit Corp
![EMPLUS-CD]() EMPLUS-CD
Panduit Corp
![03420014H]() 03420014H
Littelfuse Inc.
![10207101009]() 10207101009
Littelfuse Inc.
![BLM03AX601SZ1D]() BLM03AX601SZ1D
Murata Electronics
![74AHC74D,118]() 74AHC74D,118
Nexperia USA Inc.
![02540101Z]() 02540101Z
Littelfuse Inc.
![CJ25-82010]() CJ25-82010
Nidec Copal Electronics
![409775-1]() 409775-1
TE Application Tooling